Migros often offers attractive terms to applicants with particularly strong profiles. In our experience as a loan broker, bob Finance — also known as bob Kredit or bob credit — offers slightly more flexibility and repayment terms of up to 120 months. But interest rates are only part of the picture: creditworthiness, income, employer and budget also matter.
This comparison combines publicly available loan terms with experience from everyday credit brokerage. Mutuo’s observations are not binding commitments from lenders. Loan approval and interest rates are assessed individually.
The answer in 30 seconds
- Best prospects for an exceptionally stable, clean application: Consider Migros Bank, particularly for larger loans up to CHF 100,000.
- More flexibility with repayment terms: bob Finance offers up to 120 months rather than 84. Monthly payments may fall, while total interest costs may rise.
- Which lender is easier to qualify for? In our experience, bob is somewhat more accessible overall, but still requires good creditworthiness.
- When refinancing an existing loan: In our view, bob often has a simpler administrative process; Migros requires a final settlement statement.
Migros Bank and bob Finance: side-by-side comparison
The published loan ranges, terms and interest rates are relatively close in some respects. However, there are significant differences in how applications are assessed in practice.
A note on the name
On bob’s website, the product is called bob credit . In German-speaking Switzerland, it is also called bob Kredit or bob Finance . Throughout this article, these names refer to the same personal loan provider.
| Criteria | Migros Bank | bob Finance |
|---|---|---|
| Personal loan amount | CHF 1’000–100’000 | CHF 3’000–80’000 |
| Effective annual interest rate | 4.9–7.9% (online) | 4.7–9.9% |
| Repayment term | 6–84 months | 6–120 months |
| Age according to lender | 18–64 years | 18–64 years |
| Credit profile* | Highly selective; ideally no adverse payment history | Strict; sometimes more flexible with a strong overall profile |
| Employer verification* | Checks are relatively common | Telephone checks are rare in our experience |
| Currently in probation period | Generally not suitable | Generally not suitable |
| Hourly paid employees* | Typically 6 payslips | Typically 3 payslips |
| Fixed-term / temporary employment* | Often difficult | Often difficult |
| Refinancing an existing loan | Possible; final settlement statement required | Possible; often simpler in our experience |
| Loan payment protection | Optional | Optional |
| Key feature | Up to CHF 100,000; selective lending terms | Up to 120 months; lower monthly payments possible |
* Based on Mutuo’s brokerage experience, not published or guaranteed acceptance criteria. Published rates, loan amounts and terms: lenders’ websites, checked in October 2026.
Which lender is easier to qualify for — Migros or bob?
In our experience, bob Finance is slightly more accessible overall. This does not mean poor creditworthiness is enough. bob also has strict checks, but may accept a broader range of applicants with otherwise strong overall files.
Migros Bank is particularly selective. For people with very stable employment, a clean credit history, good income and a manageable budget, it may be an especially attractive choice.
Migros Bank
- Very clean CRIF and payment history
- Permanent employment, no probation period
- Stable employer and regular income
- Sufficient disposable income after expenses
- Seeking up to CHF 100,000
bob Finance
- Good to very good creditworthiness and a strong CRIF score
- Stable main job and solid income
- Clear, verifiable household budget
- Looking for a longer repayment term
- Seeking up to CHF 80,000
The important question is therefore not “Which lender approves more applications?” but: Which lender assesses your particular application more favourably? A rejection from Migros does not automatically mean a rejection from bob, or vice versa.
Interest, repayment term and loan amount: where are the advantages?
Which lender offers the lower interest rate?
bob advertises an effective annual rate of 4.7 to 9.9% , while Migros Bank advertises 4.9 to 7.9%for online applications. bob’s slightly lower starting rate does not automatically mean you will get a better offer. Your rate depends on an individual creditworthiness and affordability assessment.
In our experience, average interest rates for eligible Migros applicants are often lower. However, bob can offer excellent rates to customers with exceptionally strong CRIF profiles; depending on the application, the offered rate may also be higher within the advertised range.
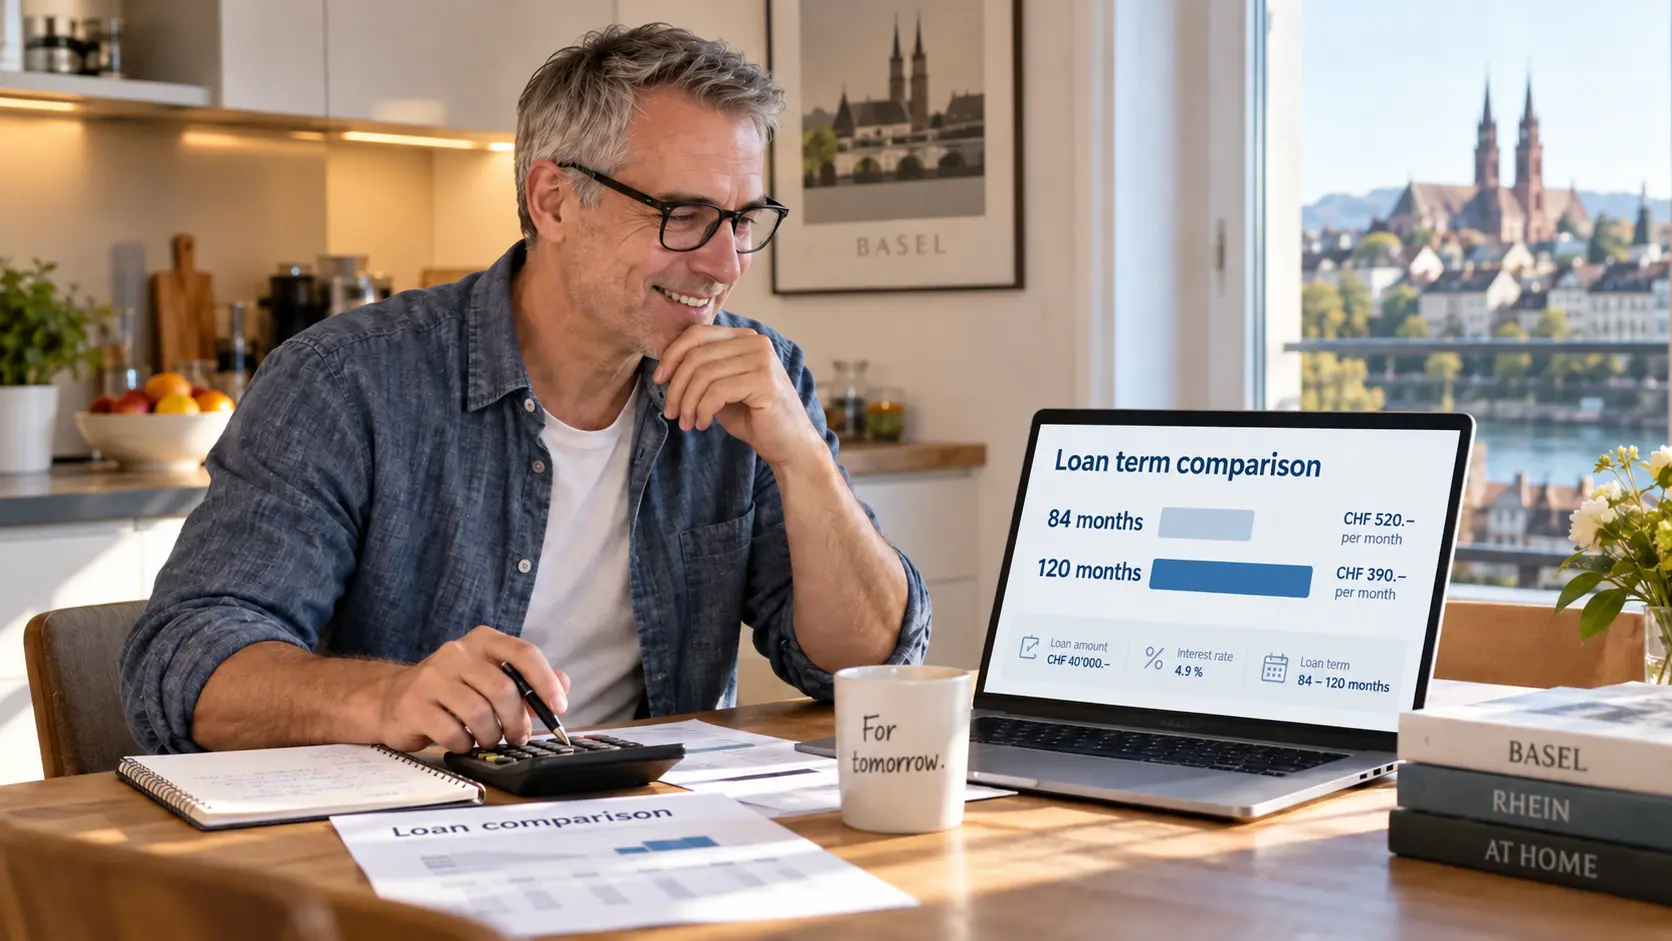
120 months with bob versus 84 months with Migros
bob’s longer term is one of the clearest product differences. Spreading the same loan amount over more months at the same interest rate reduces the monthly instalment, but generally means paying interest for longer. Always compare the overall cost too.
Under Swiss consumer credit rules, affordability is generally assessed as though the loan could be repaid within 36 months, even if the contract runs for 84 or 120 months. A longer contract can reduce the actual monthly instalment but does not automatically increase the legally affordable loan amount. See also Mutuo’s guide to loan repayment terms.
CHF 100,000 at Migros versus CHF 80,000 at bob
Migros has a clear product advantage for larger personal loans. Based on our practical experience, the administrative effort is particularly worthwhile for amounts of around CHF 15,000 or more. This is not an official minimum: Migros publicly offers loans starting at CHF 1,000.
If the requested amount is too high for the applicant’s budget, the application does not necessarily end in rejection. Both lenders may consider a counteroffer for a lower amount if the applicant is otherwise eligible. For instance, a request for CHF 70,000 could result in an offer for CHF 58,000. A counteroffer is not guaranteed.
Which lender is right for you?
Mutuo reviews your situation and helps avoid unnecessary loan applications. Free of charge and without obligation.
CRIF and creditworthiness: why two lenders reach different decisions
CRIF is a Swiss credit information agency that processes data relevant to creditworthiness, including debt collection cases and debt enforcement proceedings. CRIF does not grant loans. Migros and bob also use their own assessments and risk models, so even a good CRIF score does not guarantee approval.
Migros is particularly strict about adverse payment history
In our experience, even isolated negative CRIF payment records can make a Migros application difficult. bob may be slightly more flexible in selected cases if the overall score remains very strong and the rest of the application is convincing. None of these observations constitutes a guarantee.
Internal bank scoring may also take into account income, length of employment, employer, industry, existing loans, leasing, housing situation and the requested amount.
Request your free CRIF data report
Anyone wishing to check their data can request a personal data report from CRIF. According to CRIF, one report per year is free. It is especially useful if a rejection was unexpected or stored details may be wrong or incomplete.
Template letter: request a review of inaccurate CRIF data
Subject: Request to review and correct my CRIF data
Dear Sir or Madam,
I have reviewed my CRIF data report and ask you to investigate the following entry:
[Entry / creditor / date]I believe this information is incorrect or no longer accurate because:
[Explanation]I enclose the following documents as evidence:
[Proof of payment / creditor confirmation / other documents]Please review the information and correct any inaccurate or incomplete details in accordance with applicable law. Please inform me of the outcome in writing.
Yours faithfully,
[Full name, address, date of birth]
Paying a claim does not automatically mean that every accurate historical record must be deleted. What matters in particular is whether the data is correct, complete and up to date.
Income, employer, probation period and residence permit
Income and type of employment
We use monthly income of around CHF 4,000 as a rough practical guide for both lenders — not as an official minimum salary. The overall risk assessment and statutory budget calculation remain decisive. There is no general rule that, for example, a loan may equal ten monthly salaries.
Both lenders place particular importance on permanent employment that has not been terminated and is no longer subject to probation , together with verifiable income. In our experience, self-employed applicants and agency workers as the main borrowers are generally not suitable for these two products. A new job without a probation clause may be supported by an employment contract or employer’s letter.
Will the lender contact my employer?
In our experience, Migros verifies employment comparatively often, either directly or through plausibility checks. Telephone contact with employers is rare in the cases we see at bob. These are observations, not a guarantee about what will happen in your case.
Hourly pay, second jobs and variable earnings
For employees paid by the hour, Migros generally asks for six payslipsaccording to its published document checklist; for bob, we typically see three. Additional evidence may be requested at any time.
A stable main job with regular supplementary work — for example 70% plus 30% — can in principle be taken into account. Several small, fluctuating jobs with no clear main employer are harder to assess. Verifiable additional income such as a 13th monthly salary, recurring bonuses, commissions and shift, night or Sunday allowances should be documented correctly. For variable pay, a lender may use an average or count certain components only in part.
B permit, C permit and age
Applicants holding a C residence permit can generally apply to both lenders. A B permit may also be accepted. On its standard personal loan page, Migros requires at least two years of uninterrupted residence with a B permit. The rules applicable to an individual case should be checked before submitting an application. Cross-border commuters with a G permit are not the usual target market for these products.
Both lenders publicly state an age range of 18 to 64 years. For younger applicants, lenders also assess income, employment, creditworthiness and budget. Find out more using the Mutuo loan calculator.
Budget: rent, commuting, health insurance, maintenance and leasing
Even with excellent creditworthiness, the requested financing must be affordable. The budget assessment takes account of income, tax, rent, health insurance, travel to work, meals, children, maintenance payments and existing credit commitments.
| Budget item | Migros Bank* | bob Finance* |
|---|---|---|
| Commuting costs | Often CHF 300 in Mutuo’s experience | Minimum allowance of around CHF 200 in Mutuo’s experience |
| Health insurance | A lower actual premium does not necessarily reduce the allowance | Cantonal average; documented actual premium may be relevant |
| Shared rent | Possible; observed minimum allowance CHF 975 | Possible where the split is clearly documented |
| Divorce / maintenance | Additional documents depending on the case | Divorce decree often required early in our experience |
| Existing leasing | Included as a budget expense | Included as a budget expense |
* These budget figures reflect Mutuo’s operational experience, not publicly guaranteed standard allowances. They may change depending on the case and lender policy.
How does splitting rent work?
Where two people are named on the tenancy agreement and genuinely share the rent, both lenders may review the documented split. For a total rent of CHF 2,000 shared equally, CHF 1,000 would normally be a plausible expense for the applicant. If only the borrower is on the tenancy, the lender may count the entire rent. With Migros, we also observe a minimum allowance of CHF 975.
What about divorce, maintenance payments and a spouse’s income?
Where maintenance obligations exist, supporting documents should be prepared early. In our experience, bob often requests a divorce decree at the outset for divorced applicants. At Migros, the documents needed depend more on the individual case. Spousal income should not simply be added without checking: some types of income, such as self-employment, disability benefits or pensions, may be treated differently.
Existing loans and leasing
Leasing instalments and existing loans reduce the budget surplus available for new borrowing. Both lenders may be able to refinance existing commitments. Whether this makes financial sense must be assessed on total costs, not just a smaller monthly payment.
Refinancing: why Migros and bob handle the process differently
Both Migros and bob generally allow an existing personal loan to be paid off using new financing. One important difference is the administrative process.
At Migros Bank
For the final transfer, Migros Bank requires a final settlement statement from the existing lender showing the current outstanding balance and payment details. Migros itself recommends requesting it only after a positive credit decision has been issued.
At bob Finance
In our experience, refinancing is often simpler. Refinancing only the outstanding loan, without any additional funds, is generally possible; the exact documents depend on the case.
Migros also officially describes financing that covers at least the remaining debt. Additional funds are therefore not invariably required. In our brokerage experience, the process may differ between applicants.
When is refinancing worthwhile?
Refinancing may make sense when the current interest rate is substantially higher and creditworthiness or income has improved. We recommend comparing the current repayment balance, any settlement statement fees, the new total term and total interest costs. Checking after the loan has been running for a few months is particularly useful; six months is our rough practical guide, not a legal requirement.
When refinancing, the amount intended to repay the old loan goes to the previous lender. Any additional new funds are paid separately to the customer. For more information, see refinancing with Mutuo and our article on early loan repayment.
Debt enforcement: a CRIF report is not the same as the official register extract
A clean debt enforcement register extract does not necessarily mean that CRIF has no adverse payment data. In our experience, bob is especially strict regarding debt enforcement records, including paid cases. Migros may sometimes assess settled entries more individually, while also remaining very selective about adverse CRIF payment information.
Special feature of the Mutuo process: With a direct Migros application, the applicant needs an official debt enforcement register extract for the final assessment. Under our brokerage process, this document can initially be deferred for a preliminary review or provisional positive decision and obtained before final completion. This can avoid unnecessary work and expense.
Could you refinance your current loan at a lower cost?
We first check whether switching makes sense and which lender is realistic for your profile. Our advice is free.
What documents do Migros and bob need, and how long does it take?
A standard application from an employed borrower usually starts with valid identification and the last three payslips. Further evidence may be needed depending on the circumstances:
Migros Bank
- For hourly pay or commission, usually six payslips
- Debt enforcement register extract for the final assessment
- For refinancing: final settlement statement
- Bank statements, employment or tenancy evidence if needed
bob Finance
- For hourly pay, often three payslips in our experience
- Bank statements if income details are unclear
- Divorce decree often needed in cases involving divorce or maintenance
- Employment contract or confirmation for a new job if needed
With complete documents, we often see both lenders provide a quick initial decision, sometimes within one working day. This is not a processing guarantee; Migros Bank publicly states that applications are processed within 48 hours after all required documents have been received. Queries may extend the process.
An initial decision is not the same as receiving the funds. For personal loans covered by the Swiss Consumer Credit Act, a statutory 14-day cancellation periodapplies. Funds can be paid out only once that period has passed and final checks are successful. Payment protection insurance is optional with both lenders.
Why Mutuo assesses your application first instead of approaching two lenders at once
Submitting several loan applications does not automatically get you better terms. A better approach is to determine in advance which lender is most likely to accept your particular profile.
Before choosing where to apply, Mutuo reviews factors including:
- CRIF, payment history and debt enforcement cases
- Income, employer, probation, employment length and residence permit
- 13th monthly salary, secondary income and variable pay
- Housing costs, shared rent, health insurance and commuting costs
- Children, maintenance payments, leasing and existing personal loans
- Requested amount, repayment term and potential refinancing
What does “optimising your application” mean?
It does not mean inflating figures or making false statements. It means presenting the real situation fully and clearly — for example, documented earnings from a second job, the actual split of rent, or a new employment contract with no probation period.
We also help with lenders’ requests for additional documents and clarifications about budget items. Our aim is as few targeted loan applications as possible and financing that genuinely fits your budget.
What does it cost? Mutuo’s advice, preliminary assessment and brokerage are free for customers; no brokerage fee is charged.
Frequently asked questions: Migros Bank or bob Finance?
Is it easier to get approved by Migros or bob?
Based on Mutuo’s experience, bob is somewhat more accessible. Both lenders still require good creditworthiness, sufficient income and an affordable budget. Approval cannot be guaranteed.
Which lender has the lower interest rate?
bob advertises 4.7–9.9%, while Migros advertises 4.9–7.9% effective annual interest on online applications. Your actual rate is decided after an individual assessment. We often see lower average rates for eligible Migros applicants.
Which lender offers a 120-month repayment term?
bob Finance. Migros Bank offers a maximum of 84 months. A longer term can reduce monthly payments but normally increases the total interest cost.
Will a 120-month term automatically allow me to borrow more?
No. Under consumer credit rules, affordability is generally assessed on the basis of repayment within 36 months. The contractual repayment term may still be longer.
What is the maximum loan amount?
Migros advertises up to CHF 100,000 and bob up to CHF 80,000. The amount actually available depends on your individual profile and affordability assessment.
Can I get a loan with a B residence permit?
In principle, yes, if the relevant conditions are met. On its regular loan page, Migros specifies at least two uninterrupted years of residence with a B permit. Your individual position should be checked before applying.
Can I borrow while still in a probation period?
An ongoing probation period is generally unsuitable at Migros and bob. If a new employment contract expressly has no probation period, the lender may nonetheless consider the case.
Will the lenders call my employer?
In our experience, employment checks are relatively common at Migros, while telephone enquiries are rare at bob. This cannot be guaranteed for any individual case.
How many payslips do I need if I am paid hourly?
Migros specifies six payslips for hourly pay or commission. At bob, we typically see three. Further documents may be required.
Could bob approve me after a Migros rejection?
Yes. The two lenders have different scoring models. A refusal at one does not automatically predict the other’s decision. Reviewing the file before applying again is sensible.
Can I refinance my current loan with Migros or bob?
Yes, with either. Migros needs a final settlement statement from the existing lender for the transfer. bob is often administratively simpler in our experience. Migros also publicly describes refinancing without compulsory additional cash.
Is the CRIF personal data report free?
According to CRIF, an individual can request one free report per year. Incorrect or incomplete data can be submitted for review and correction.
How long until I receive the money?
An initial decision may be quick once the application is complete. However, loans subject to the Consumer Credit Act require the statutory 14-day cancellation period to expire before payment. Further checks can take longer.
Does Mutuo charge for advice or brokerage?
No. Mutuo’s preliminary assessment, advice and loan brokerage are free for customers.
Conclusion: Migros Bank or bob Finance?
Migros Bank is particularly attractive for exceptionally clean, stable and well-documented applications, especially when competitive rates or amounts up to CHF 100,000 are the priority. bob Finance can suit good credit profiles with a somewhat wider acceptance range and is especially interesting when a term of up to 120 months could reduce the actual monthly burden.
There is no universal winner. The lowest advertised rate is not necessarily the rate you will receive. The best lender is one that can responsibly finance your circumstances at suitable overall terms.
Don’t apply at random
Mutuo reviews your situation and selects a suitable application strategy. Free, without obligation and personal.
- Migros Bank – personal loan, features and eligibility criteria
- Migros Bank – application documents
- bob Finance – personal loan, rates and terms
- CRIF – personal data report
Details about employer contacts, internal credit assessments, budget allowances and individual documentation requirements are based on Mutuo’s brokerage experience (observations as of October 2026). These may change and are not a binding loan offer. Lending is prohibited where it would lead to over-indebtedness (Article 3 of the Swiss Unfair Competition Act). Images used in this article are illustrative.