Bank Now vs Cembra
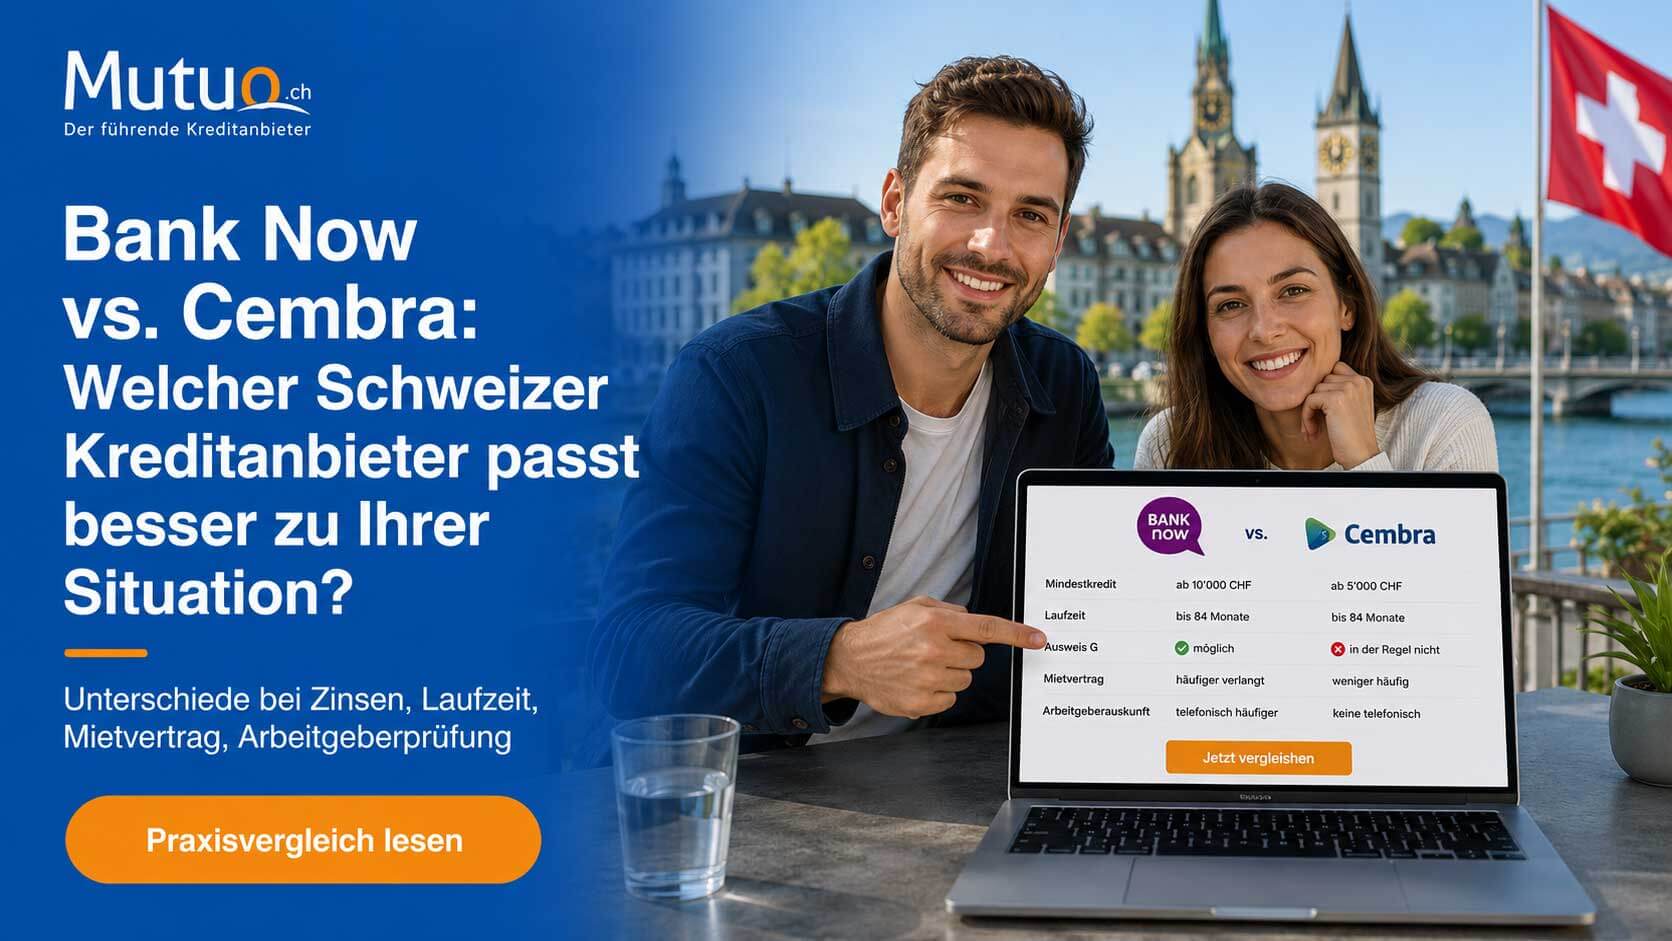
Bank Now vs. Cembra: which Swiss lender best suits your situation?
Our practical experience: as of July 2026
This article is based on Mutuo’s daily work as an independent Swiss credit broker. The differences described reflect practical experience gained from handling loan applications. Banks’ acceptance criteria, interest rates and internal processes may change at any time.
Are you looking to take out a personal loan and wondering whether Bank Now or Cembra is the better choice? Many people in Switzerland ask this question, as both banks are among the largest and best-known providers of consumer credit.
The short, honest answer is that there is no clear winner for most standard cases. Bank Now and Cembra are far more similar in many areas than many prospective borrowers expect. The difference often lies in a few specific criteria, internal scoring and the quality of the submitted application, rather than one bank being generally stricter or better.
That is precisely why this comparison is structured differently from many typical SEO articles. We do not artificially claim that one bank is better in every respect. We show where genuine differences exist, where both banks make practically identical decisions and when an application through Mutuo can help avoid unnecessary applications and rejections.
The key points at a glance
The detailed side-by-side comparison
The main finding: the banks are more similar than many people think
Many customers want a simple answer: is Bank Now stricter than Cembra? Is Cembra cheaper? Does one bank generally approve loans more easily?
Based on our practical experience, the more honest answer is that Bank Now and Cembra are very similar in most standard cases. Differences do exist, but they concern specific situations. These details can be decisive in an individual case.
A common misconception
Many people assume that choosing between Bank Now and Cembra automatically determines approval or rejection. In practice, meeting the minimum requirements, having a suitable budget and submitting a complete, accurate application are more often decisive.
Where Bank Now may have clear advantages
1. Cross-border workers with a G permit
The G permit reveals one of the clearest differences. In our experience, Bank Now generally also finances cross-border workers. Cembra is usually not an option here. Anyone seeking a Swiss personal loan as a cross-border worker should therefore have their options assessed with Bank Now or other suitable providers.
2. Pensioners
For pensioners, Bank Now is often the first choice in our experience. Generally, loans at both banks must be repaid by age 65. A particular feature of Bank Now is that financing up to age 70 may be possible under certain conditions for retired people or customers with a pension award notice.
3. Larger loan amounts
For larger loan amounts, we see a slight advantage for Bank Now in some cases. This difference is small and should not be generalised. Income, budget, creditworthiness, existing commitments and the overall quality of the application remain decisive.
Where Cembra may have clear advantages
1. Smaller loan amounts
In our experience, Cembra starts at CHF 5’000. Bank Now only becomes an option from CHF 10’000. For anyone seeking a loan between CHF 5’000 and CHF 9’999, Cembra therefore offers a clear practical advantage.
2. Missing tenancy agreement
In practice, Bank Now requests tenancy agreements more often than Cembra. If the customer does not include the agreement straight away, this often leads to further questions or delays at Bank Now. In such cases, Cembra can often be the more pragmatic first option.
Mutuo’s tip
If the tenancy agreement is available, it should be submitted with the application. Particularly at Bank Now, this can avoid further questions and speed up processing.
3. Multiple employers
In our experience, Cembra is slightly more flexible with customers who have multiple employers, for example two part-time jobs. However, all income must be stable, understandable and fully documented.
4. PPI/payment protection insurance
If a customer expressly wants payment protection insurance, or PPI, Cembra may offer advantages. In our experience, Cembra’s PPI is more flexible because it can be added or cancelled at any time.
Loan amounts: CHF 5’000, CHF 10’000 and loans above CHF 80’000
There is a simple but important difference in loan amounts. Bank Now starts at CHF 10’000. Cembra starts at CHF 5’000. This matters for customers with smaller financing needs.
Neither bank has a simple, rigid upper limit that applies equally to every customer. The maximum loan amount depends on individual borrowing capacity, budget, creditworthiness and the legal classification. Loans above CHF 80’000 fall outside the standard scope of the Consumer Credit Act and must be assessed separately.
Mutuo’s practical experience
For larger loan amounts, the application matters more than the brochure. A customer with a good income may still be rejected if leasing, housing costs, maintenance obligations or existing loans place a heavy burden on the budget.
Loan terms: up to 84 months at both banks
Bank Now and Cembra are very similar in terms of duration. Both generally offer loan terms of up to 84 months. Neither offers a longer term of 120 months. Anyone who needs 120 months must consider other providers.
A very short term is not always sensible. Many customers want to repay their loan as quickly as possible and therefore choose a high monthly payment. A longer term can reduce the monthly burden and help keep the budget sustainable.
For higher-risk customer groups, however, both banks may reduce the maximum term of 84 months. Repayment must also generally be completed by age 65. Bank Now has a special practice for pensioners or customers with a pension award notice, allowing repayment up to age 70 in some cases.
Interest rates: small differences between Bank Now and Cembra, larger differences with other banks
Based on our current practical experience, Bank Now and Cembra are both relatively expensive. Many offers are around 8.9 % to 9.9 %. For the same creditworthiness, Cembra currently often offers a slightly lower rate than Bank Now. However, the differences between the two banks are usually not huge.
Anyone seeking a substantial reduction in interest should compare more than just Bank Now and Cembra. With an excellent credit profile, other banks such as bob Finance or Migros Bank may offer significantly more attractive terms. However, these banks must also suit the application to avoid an unnecessary rejection.
Careful preparation of the application and a targeted request for a lower rate can sometimes secure a better interest rate. There is no guarantee. Creditworthiness, budget, bank policy, documents and choosing the right bank are decisive.
A direct route to the best offer with Mutuo
Mutuo checks not only Bank Now and Cembra, but also whether other banks with lower rates could suit the individual customer. This allows customers to receive several suitable offers rather than risk a rejection by applying to the wrong bank themselves.
Budget calculations: why details matter
Bank Now and Cembra calculate household budgets in more detail than many other banks. Some institutions use flat-rate allowances. Bank Now and Cembra, however, often consider actual costs, for example health insurance, commuting and meals.
Depending on the situation, this can be better or worse. People with very low actual costs may benefit. High car costs, health insurance premiums or housing costs, however, may lead to a less favourable budget assessment.
Health insurance premiums
Commuting
Meals
For meals away from home, Bank Now and Cembra also focus more on the actual situation than banks that work exclusively with flat-rate allowances.
Why an expert can help
An experienced credit adviser can prepare the application correctly: shared rent in a shared household, verifiable additional income, actual health insurance premiums, commuting and meals. The aim is to present the real situation completely and clearly, without changing the information.
Documents: what Bank Now and Cembra really want to see
The documents required depend strongly on the customer’s circumstances. Typical documents include payslips, a copy of identification, proof of health insurance, the tenancy agreement, bank statements and additional evidence for special situations.
Customers generally do not have to submit a debt enforcement register extract themselves. If required, the bank requests this information as part of the credit assessment or checks the relevant data with the customer’s consent.
Tenancy agreement
The tenancy agreement is one of the most important documents for quick processing. In our experience, Bank Now requests it more often than Cembra. Including it immediately can avoid further questions.
Owners of limited companies
For owners or co-owners of a GmbH, AG or similar company, there is an important difference. In our experience, Bank Now generally requires a tax assessment. At Cembra, payslips may already be sufficient for an assessment, depending on the application. However, Cembra can also request additional documents.
Sole proprietorships and conventional self-employment
For conventional self-employed applicants, for example sole traders, Bank Now and Cembra are very similar in our experience. These applications are generally more complex than those of ordinary employees and should be well prepared.
Employer checks: one of the biggest operational differences
In our experience, Bank Now checks employers by telephone considerably more often than Cembra. Cembra makes practically no telephone enquiries to employers. Bank Now may carry out such checks on a sample basis, but they are not standard for every application.
In our experience, Bank Now may carry out a discreet employer check on a sample basis. Cembra only very rarely contacts employers by telephone.
Residence permits: B, C and G permits
Swiss citizens and C permits
In our experience, there is no significant difference between Bank Now and Cembra for Swiss citizens and people with a C permit.
B permit
For a B permit, both banks are also very similar. Around two years of residence is often used as a guideline. For shorter periods of residence, Cembra may be worth trying in individual cases, but there is generally no major difference.
G permit
The G permit is one of the clearest differences. In our experience, Bank Now generally finances cross-border workers, while Cembra usually does not.
Age, young customers and pensioners
In our experience, Bank Now accepts loan applications from age 20 and assesses customers up to around age 25 particularly strictly. Cembra assesses young customers more on their overall circumstances: employment, income, budget, housing and previous creditworthiness.
For pensioners, Bank Now is often the better first choice. Particularly relevant is the possibility of repaying up to age 70 under certain conditions, if the customer has a pension award notice or is retired.
Employment: probation, temporary work, fixed-term contracts and multiple jobs
Probationary period
Neither bank accepts applicants during their probationary period. Based on our practical experience, neither Bank Now nor Cembra provides financing during the probationary period.
Temporary work
Temporary employees are generally eligible at both banks. In our experience, however, at least 12 months with the same employer is usually required. Overlooking this point can lead to an unnecessary rejection.
Fixed-term employment contracts
Both banks are very cautious with fixed-term employment contracts. In principle, the loan must be fully repaid when the employment ends. In practice, financing is therefore usually difficult.
Multiple employers and multiple part-time jobs
We see a slight advantage for Cembra with multiple employers. Cembra is slightly more flexible in these cases. All income must nevertheless be stable, verifiable and understandable.
Hourly pay and additional income
There is no significant difference for hourly pay and regular additional income. What matters is that the income is stable and can be documented.
Occupations and industries
Bank Now and Cembra assess occupations in broadly similar ways. More stable jobs are better. Public service, pharmaceuticals or similarly stable employers tend to have a positive effect. Hospitality and other industries with more frequent job changes or fluctuating income can be more challenging.
However, the job title alone is not decisive. The overall situation matters: length of employment, income, budget, creditworthiness and the clarity of the documents.
Spouses, marital status, children and maintenance payments
For married customers, both banks may take the spouse’s income into account, provided the necessary documents are submitted and the spouse gives consent.
The applicant does not have to personally declare the spouse’s debts or leasing contracts. With the necessary consent, banks can check relevant information as part of the credit assessment, for example through the ZEK. Based on your experience, however, the spouse’s commitments are generally not included directly in the applicant’s budget.
Marital status and family circumstances are particularly prone to errors. Separated is not the same as divorced. Being single, married, separated or divorced may have different implications. Children and maintenance payments must be declared fully and accurately.
Leasing, existing loans and the ZEK
Customers often underestimate leasing. A leasing contract is recorded in the ZEK and its monthly payment reduces the available budget. This can reduce the possible loan amount or lead to a rejection.
In our experience, Bank Now and Cembra treat leasing commitments practically identically. Existing personal loans are also assessed similarly by both banks. Both can repay existing loans through loan refinancing, provided the application is suitable.
All loan applications, responses, outstanding loans, loan amounts and instalments are recorded in the ZEK. Too many applications, particularly if rejected, may worsen the starting position for further applications. A careful preliminary assessment is therefore important.
Why the same customer is accepted by one bank and rejected by the other
Although Bank Now and Cembra are similar, the same customer may receive approval from one bank and a rejection from the other. This is rarely due to a single factor. Usually, many small factors work together.
A previous good payment history with the same bank may help, but does not guarantee a new approval or better terms. The current financial situation remains decisive.
Common reasons for rejection
A good income alone is not enough. In our experience, the following are among the most common reasons for rejections at Bank Now and Cembra:
- Probationary period: loans are practically unavailable at both banks during probation.
- Loan amount too high: the desired amount does not match the budget or creditworthiness.
- Insufficient income: the income is not enough for the amount requested.
- Too many outstanding commitments: existing loans, leasing or other obligations put too much pressure on the budget.
- Poor payment history: negative experiences are a major problem at both banks.
- Debt enforcement proceedings: relevant proceedings may lead to a rejection.
- Insufficient creditworthiness: the overall assessment is not favourable enough.
- Wrong bank: the bank’s minimum requirements were not checked before applying.
The most important advice for new credit advisers
Check the minimum requirements carefully. Many rejections occur because an application is submitted to a bank whose minimum criteria are not met, rather than because the customer cannot obtain a loan at all.
Common mistakes in loan applications
Many follow-up questions and delays arise from incomplete or inaccurate information. Particularly common examples include:
A complete application can considerably speed up processing. The tenancy agreement is particularly important because Bank Now often requests it.
When Bank Now and Cembra are not the first choice
Bank Now and Cembra are good providers for many customers. However, there are situations where other banks are a better fit.
Apply directly to Bank Now or Cembra, or speak to Mutuo first?
Our clear recommendation: have Mutuo assess your situation first.
Mutuo carries out a preliminary assessment before applying to a bank. We check creditworthiness, minimum requirements, documents and the customer’s specific situation. Only then do we decide which bank is the best fit and whether Bank Now, Cembra or another provider offers the best chances of success and the best terms.
Why this is better for customers
Why banks benefit too
Banks receive complete, better-prepared applications. This makes assessment easier and can speed up processing. For customers, it is a win-win situation: less effort, better preparation, several offers and a better chance of suitable terms.
FAQ: Bank Now vs. Cembra
Is Bank Now better than Cembra?
Not in general. Both banks are very similar for many standard customers. What matters is which bank is better suited to the specific situation.
Is Cembra better than Bank Now?
There is no general answer to this either. Cembra has advantages for smaller loan amounts, missing tenancy agreements, multiple employers and PPI. Bank Now has advantages for G permits, pensioners and sometimes higher amounts.
Which bank is cheaper?
For the same creditworthiness, Cembra currently often offers a slightly lower rate in our experience. The differences between Bank Now and Cembra are usually smaller than those between these banks and other providers such as bob Finance or Migros Bank.
Which bank offers smaller loans?
Cembra. Cembra starts at CHF 5’000, while Bank Now starts at CHF 10’000.
Which bank offers a 120-month term?
Neither. Bank Now and Cembra offer a maximum of 84 months.
Which bank accepts a G permit?
Bank Now. In our experience, Cembra generally does not finance G permit holders.
Which bank is better for pensioners?
In our experience, Bank Now is often the first choice for pensioners.
Which bank is more likely to request the tenancy agreement?
Bank Now requests tenancy agreements considerably more often than Cembra.
Which bank is more likely to call the employer?
Bank Now carries out telephone employer checks considerably more often. Cembra practically never does this.
Is an employer check always standard at Bank Now?
No. It is carried out on a sample basis or when the application requires it.
Is Cembra better for multiple employers?
In our experience, Cembra is slightly more flexible for multiple employers.
Which bank is better for PPI?
Cembra may offer advantages because PPI can be added or cancelled more flexibly.
Can I get a loan during my probationary period?
No. In our experience, loans during probation are practically unavailable at Bank Now and Cembra.
Can I get a loan with a fixed-term employment contract?
Usually not in practice, as the loan must be repaid before the employment ends.
Do both banks accept temporary employees?
Yes, in principle. In our experience, however, around 12 months with the same employer is usually required.
Are there differences for B permits?
Hardly any. Both banks assess B permits very similarly, often requiring a sufficient period of residence.
Are there differences for C permits?
No, practically none in our experience.
Are there differences for hourly pay?
No. Income stability and verifiability are decisive.
Are there differences for additional income?
No. Regular, documented additional income can be taken into account by both banks.
Are there differences for home ownership?
No. Both banks assess home ownership similarly.
Does owning a home automatically help?
No. It can be positive, but does not replace a sustainable budget and good creditworthiness.
How do both banks treat leasing?
Similarly. Leasing is recorded in the ZEK and reduces the available budget.
Do I have to declare existing loans?
Existing loans are visible in the ZEK and are taken into account during assessment.
Can I get a new loan despite having an existing loan?
Yes, often through loan refinancing. The budget is decisive.
Which bank is better for loan refinancing?
Bank Now and Cembra are practically identical here. Other banks may have different processes.
Why does one bank reject an application while the other approves it?
Because different scorecards, data sources and payment histories play a role. Usually, the combination of many small factors determines the outcome.
Does a previous loan paid correctly guarantee a new approval?
No. It may help, but is no guarantee. The current situation remains decisive.
Which minimum requirement is often overlooked?
It depends on the case. Probation, income, too many outstanding commitments, leasing or missing documents are often relevant.
Do I have to submit the debt enforcement register extract myself?
Generally not. The bank checks relevant information itself, with the necessary consent.
Can I apply to Bank Now and Cembra at the same time?
Yes, but too many or poorly prepared applications can be disadvantageous, particularly if they lead to rejections.
Why does applying through Mutuo make sense?
Mutuo first checks the minimum requirements, creditworthiness and documents. This helps avoid unnecessary applications and rejections; applications are only submitted to suitable banks.
Does Mutuo cost extra?
No. Applying and receiving support through Mutuo is free for customers.
Can Mutuo obtain better terms?
Terms through brokers are often attractive; based on Mutuo’s experience, the average interest rate is lower. There is no guarantee.
Which document speeds up processing the most?
The tenancy agreement, particularly at Bank Now.
Which details frequently cause problems?
Marital status, children, maintenance payments, housing costs, shared rent, additional income and leasing.
Conclusion
Bank Now and Cembra are both important Swiss personal loan providers. The biggest mistake, however, would be to portray them as completely different banks. Our practical experience shows that they are very similar in many respects. That is precisely why the details matter.
Bank Now is particularly relevant for G permits, pensioners and, in some cases, higher amounts. Cembra is stronger for smaller loan amounts, missing tenancy agreements, multiple employers and flexible PPI. In many other areas, there are hardly any differences.
The most important factor for success is therefore not which bank is generally better. What matters is whether the bank suits the specific application. Carefully checking minimum requirements, budget, documents and creditworthiness before applying avoids unnecessary applications and rejections and increases the chance of a suitable offer.
This is precisely where Mutuo adds value: a free preliminary assessment, careful application preparation, suitable bank selection, several offers and personal support. For customers, this means less effort, less risk of unnecessary applications and rejections, and often a better chance of suitable terms.
Verwandte Themen


 Currently from 4.5%
Save on interest now
 Your loan request is non-binding and free of charge
 Over 55216 customers.
For 30 years

- Visit our office:
- Mutuo AG
- CLARASTRASSE 19
- 4005 BASEL

- Telephone:
- 061 681 51 83
- 061 692 57 88

- Fax
- 061 692 57 77


10‘000 CHF 12 Monate Laufzeit:
Der Zins (Gesamtkosten) sind zwischen CHF 240 und CHF 574. Der Zinssatz 4.5 % – 11.95 %.
Die Rate ist zwischen CHF 855.- und CHF 868. im Monat.
Die Kreditvergabe ist verboten, falls diese zur Überschuldung führt. (Art. 3 UWG).